
The top beverage trends of 2026 come from daily habits more than from novelty. Over the past few years, shifts in health priorities, work patterns, and social routines have narrowed which drinks consumers buy again. For your team, that means growth sits with formats that do one clear job inside an existing routine, and that a retail buyer can justify listing.
Key takeaways
- Morning and convenience lead US beverage demand. Nearly 1 in 10 US non-alcoholic beverage consumers (9.9%) tie their drink to the morning, up 17% on last year, and convenience grew 18%.
- Precision wellness drinks target one outcome, such as energy or gut health, inside a routine consumers already have. Protein coffee and prebiotic soda are the clearest examples.
- Consumer interest and menus can move in opposite directions. Prebiotic soda reaches 35% fewer US carbonated drink consumers than a year ago, while the share of US restaurants serving it rose 30%.
- Among US functional tea consumers, energy and wellness each grew about a fifth in the past 12 months, while broad healthy and gut health claims lost ground.
- Explicit sustainability claims are cooling with US beverage consumers, down 24% on last year. Packaging changes buyers can verify at shelf, like aluminum cans replacing plastic bottles, carry the eco story more clearly than ingredient claims.
- Matcha reaches 1.4% of US beverage consumers and nearly 1 in 10 US restaurants (8.1%), and the Tastewise forecast has demand about 11% higher by September 2027.
Key beverage innovation terms defined
Precision wellness
A beverage approach focused on a specific, measurable health outcome rather than a broad wellness claim. Examples include post-workout drinks with defined protein content, gut health sodas with prebiotic positioning, or sleep beverages formulated with melatonin or magnesium.
Routine-led formats
Beverage formats designed to fit into habits consumers already have instead of creating new occasions. Examples include protein coffee in the morning, prebiotic soda at lunch, or functional tea in an evening wind-down routine.
Functional beverages
Drinks positioned around a clear physiological benefit such as energy, hydration, gut health, focus, calm, or recovery. In beverage innovation trends, functional beverages scale best when the benefit is easy to understand and tied to a familiar format.
Key takeaways
- Morning and convenience lead US beverage demand. Nearly 1 in 10 US non-alcoholic beverage consumers (9.9%) tie their drink to the morning, up 17% on last year, and convenience grew 18%.
- Precision wellness drinks target one outcome, such as energy or gut health, inside a routine consumers already have. Protein coffee and prebiotic soda are the clearest examples.
- Consumer interest and menus can move in opposite directions. Prebiotic soda reaches 35% fewer US carbonated drink consumers than a year ago, while the share of US restaurants serving it rose 30%.
- Among US functional tea consumers, energy and wellness each grew about a fifth in the past 12 months, while broad healthy and gut health claims lost ground.
- Explicit sustainability claims are cooling with US beverage consumers, down 24% on last year. Packaging changes buyers can verify at shelf, like aluminum cans replacing plastic bottles, carry the eco story more clearly than ingredient claims.
- Matcha reaches 1.4% of US beverage consumers and nearly 1 in 10 US restaurants (8.1%), and the Tastewise forecast has demand about 11% higher by September 2027.
Enhanced beverages
Traditional beverage formats with one added benefit, ingredient, or claim. Examples include electrolyte water, vitamin-enhanced juice, or coffee with added adaptogens. The difference from fully functional beverages is that the enhancement supports the format rather than redefining it.
Stacked functional claims
The use of more than one benefit within the same product, such as energy plus gut health or hydration plus immunity. These products can work, but only when one benefit remains primary and the rest support it.
Clean label beverages
Drinks built around ingredient transparency, recognizable components, and fewer artificial additives. In functional drink development, clean label expectations increasingly sit alongside performance claims rather than replacing them.
Botanical beverages
Beverages using plant-based ingredients such as herbs, flowers, roots, or fruit botanicals for flavor, function, or both. These products perform best when the botanical ingredient contributes to taste as well as positioning.
Sustainable beverage packaging
Packaging designed to reduce waste, improve recyclability, lower material use, or create operational efficiency. This includes lightweight bottles, recyclable cans, refill systems, and formats designed for lower shipping or storage impact.
Analyzing evolving beverage industry trends and market shifts
The biggest beverage industry trends of the past 12 months are about when and how people drink, more than what is new. Across the Tastewise US consumer panel, nearly 1 in 10 non-alcoholic beverage consumers (9.9%) connect their drink to the morning, up 17% on last year. Convenience grew 18% and ease of preparation grew 22% over the same period. Taste as a stand-alone reason to choose a drink fell 21%, so a flavor story now needs a routine attached to it.
Inside the category, attention is moving away from broad staples. Tea still reaches nearly 1 in 10 US non-alcoholic beverage consumers (7.6%), but it lost 8% of them since last year, and fruit juice fell 12%. Customizable drinks grew instead. Dirty soda reaches 0.21% of the same consumers and more than tripled, and Diet Coke rose 41%.
Each beverage industry trend also moves at a different speed by channel. On shelf, caffeine was the most common claim on new US beverage launches in the past 12 months, ahead of sparkling and energy. On menus, some drinks keep spreading after consumer interest cools, as the prebiotic soda figures further down show.
For your team, this means the top beverage trends in one channel can be fading in another. A concept validated on consumer demand alone can reach shelves after consumers have moved on. Reading beverage industry data across consumers, menus, and shelf together shows which stage a trend is in before you commit a launch slot. The commercial case for tracking these shifts is covered in our guide to beverage business insights.
What is precision wellness in beverages?
Precision wellness in beverages refers to products designed to deliver a specific, measurable functional benefit within an existing consumption routine. Unlike general wellness drinks, precision wellness concentrates demand around outcomes such as energy, gut health, or recovery, rather than broad “better-for-you” positioning.
Across the Tastewise US consumer panel, specific outcomes are growing while vague ones shrink. Energy reaches about 1 in 20 US non-alcoholic beverage consumers (5.6%), up 10% compared with last year. Detox, one of the broadest wellness claims, fell 43% among US beverage consumers over the same period. The growth sits with formats that already fit daily habits.
Here’s what this means for beverage brands:
- Products without a clear role in a routine give buyers less reason to list them.
- Wellness demand is gathering around a few named outcomes, such as energy and focus.
- A single, specific benefit is easier to defend at shelf than a broad one.
Traditional vs. precision wellness beverages
| Traditional Wellness | Precision Wellness |
|---|---|
| “Supports overall health” positioning | Targets one clear outcome (e.g., gut health, energy) |
| Example: Vitaminwater | Example: OLIPOP (prebiotic soda) |
| Requires explanation | Immediately understood |
| Drives trial | Drives repeat purchase |
| Harder to defend at shelf | Easier to justify to buyers |
Which functional beverages are succeeding in 2026?
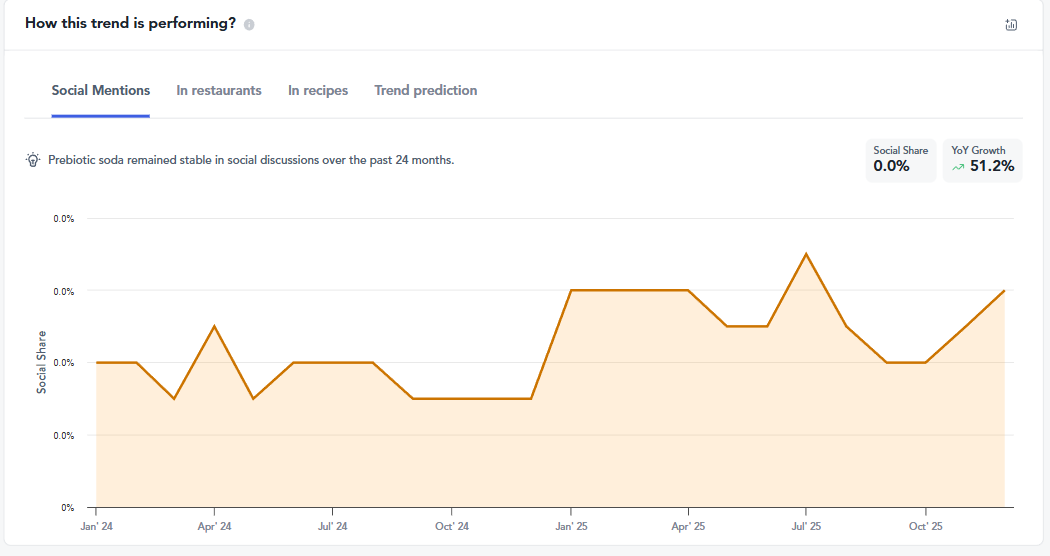
Functional beverages succeed when the benefit is explicit and built into a format consumers already drink. For instance, when asking does Gen Z drink less coffee, the answer lies in how they drink it. Protein coffee reaches 0.44% of US coffee consumers, and the share of US restaurants serving it grew 9% in the past year. Prebiotic soda puts gut health into a familiar refreshment occasion, and the share of US restaurants serving it rose 30% in the past 12 months.
Consumer interest tells a different story. Prebiotic soda reaches 35% fewer US carbonated drink consumers than a year ago, and protein coffee dipped 8% among coffee consumers. Menus are still adding both drinks while consumer interest cools, so check consumer and menu data together before you size a launch.
Here’s what this means for beverage brands: consumers mostly upgrade drinks they already buy. In both cases the format does most of the work. Coffee and soda already have established frequency, so adding a function makes the drink more relevant without asking anyone to change a habit. That makes these products easier to justify internally and easier to sell into retail, where repeat velocity determines shelf space.
How do multiple wellness benefits scale without losing clarity?
Functional tea shows how one drink can carry more than one benefit without confusing the consumer. Among US functional tea consumers, nearly 1 in 3 (31%) choose it as a healthy drink, nearly 1 in 4 (24%) for energy, and about 1 in 5 (22%) for wellness. Energy and wellness each grew about a fifth in the past 12 months, while the broad healthy claim fell 20% and gut health fell 22%.
These benefits sit together because tea is already a habitual drink across dayparts, from a morning energy cup to an evening wind-down. Calm still reaches about 1 in 10 functional tea consumers (10.5%), so a morning energy tea and an evening calm blend can share one brand without competing.
Here’s what this means for beverage brands: a second or third benefit adds value only when the product already has a clear role in the consumer’s routine. Without that anchor, extra claims make the pack harder to read.
How do routine-led formats differ from standalone wellness drinks?
Routine-led formats are beverages designed to fit into existing habits, while standalone wellness drinks require consumers to create new occasions. The difference between the two is adoption friction.
Routine-led formats such as protein coffee, prebiotic soda, and functional tea succeed because they align with moments that already exist, such as morning coffee, refreshment breaks, or evening wind-down. Standalone wellness drinks, including tonics or supplement-style beverages, often struggle because they require new behaviors that are harder to sustain.
The key difference is repeatability. Routine-led formats inherit frequency from the behavior they replace, while standalone drinks must build frequency from scratch.
Here’s what this means for beverage brands: the fastest path to scale is adding a function to a ritual consumers already have. Products that match established consumption patterns are easier for consumers to adopt and easier to justify to buyers, which supports steady velocity at shelf.
Functional vs. enhanced beverages
| Enhanced Beverage | Functional Beverage |
|---|---|
| Adds a benefit to an existing drink | Built around a specific benefit |
| Example: Smartwater (Coca-Cola) – hydration + electrolytes | Example: Huel Ready-to-Drink – complete nutrition |
| Example: Vitaminwater (Coca-Cola) – vitamins added to water | Example: Premier Protein Shakes – protein for satiety/recovery |
| Function is secondary | Function is the reason to buy |
| Maintains the same use occasion | Defines the use occasion |
| Lower consumer commitment | Higher intent-driven consumption |
What sustainability innovations are consumers actually buying?
Sustainability innovations work when they are specific, visible, and tied to the product’s role. Across the Tastewise US consumer panel, explicit eco claims are cooling. Sustainability as a reason to choose a drink reaches 0.54% of US beverage consumers, down 24% on last year, and organic fell 19%. Natural is the largest of these cues at 1.98%, and it slipped 7%.
Consumers respond to sustainability when it supports something they already value, such as taste or ingredient quality. Asking them to choose a drink for its environmental impact alone is a harder sell.
Here’s what this means for beverage brands: build sustainability into the product experience itself. When it supports an existing purchase driver, it strengthens the proposition. When it stands alone, it struggles to convert
How do eco-friendly ingredients attract attention?
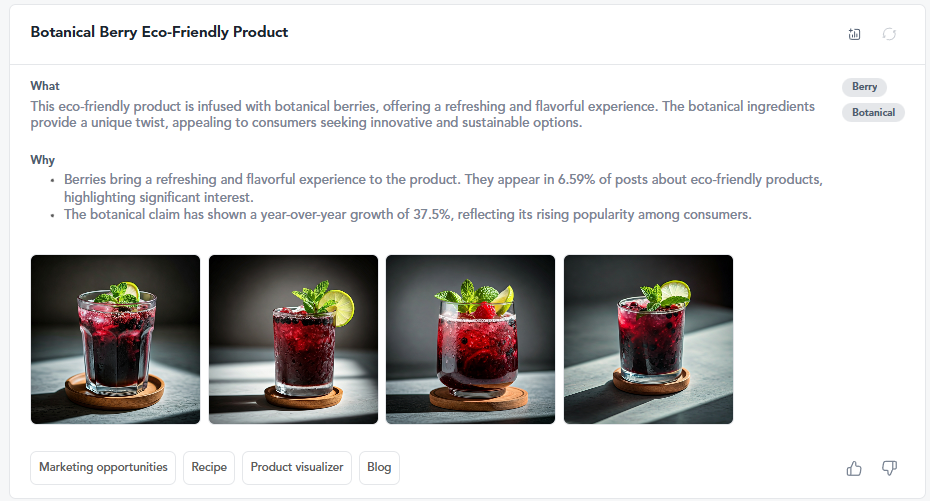
Concepts that combine botanical ingredients with sustainability cues can generate early interest, particularly in social discovery. A botanical berry beverage positioned around eco-friendly sourcing and natural ingredients is one example, where the botanical carries the flavor and the sourcing story comes second.
This type of positioning works best when the ingredient choice reinforces an existing consumption motivation, such as refreshment or flavor, rather than asking consumers to value sustainability as a standalone benefit.
Where do sustainability concepts fail to scale?
However, sustainability-led beverages struggle to scale when the claim remains abstract. Eco-friendly language that is not supported by tangible packaging choices, sourcing transparency, or functional relevance often fails to move beyond early engagement. Without a clear explanation of what makes the product more sustainable, and why that matters in daily use, interest remains surface-level and inconsistent.
This is where many sustainability concepts stall: the consumer understands the intent but cannot articulate the value, and buyers cannot defend the SKU decision. As a result, sustainability must be articulated in a way that connects directly to usage, cost, or operational benefit. Without that structure, even strong intent does not translate into repeat purchase or retail support.
Why is packaging innovation outperforming ingredient-led sustainability?
According to broader beverage innovation patterns, sustainable packaging solutions are outperforming ingredient-led sustainability narratives. Lightweight materials, recyclable formats, and packaging designs that reduce waste or improve storage efficiency are easier for retailers and operators to justify. These changes directly affect logistics, shelf efficiency, and operational cost, making sustainability actionable rather than aspirational.
When sustainability shows up through packaging decisions, it becomes easier to communicate internally, easier to sell externally, and easier for consumers to recognize at the point of purchase. Sustainability becomes commercially viable when it is built into the physical product experience. Packaging makes sustainability tangible, which makes it easier to communicate internally, easier to sell externally, and easier for consumers to recognize at shelf.
Sustainability claims vs. proven eco-benefits
| Sustainability Claim | Proven Eco-Benefit |
|---|---|
| Broad language (“eco-friendly”, “natural”) | Specific, visible change |
| Example: innocent Drinks – “natural, responsibly sourced” messaging | Example: Liquid Death – aluminum cans replacing plastic bottles |
| Example: Honest Tea (legacy positioning) – organic, ethical sourcing | Example: Boxed Water – carton-based packaging reducing plastic use |
| Ingredient-led messaging | Packaging or format-led proof |
| Requires belief | Easy to verify at shelf |
| Harder for buyers to quantify | Easier to defend in retail conversations |
How is flavor innovation contributing to beverage growth?
Flavor experimentation continues to play a role in beverage innovation heading into 2026, but adventurousness alone is not what’s driving adoption. The flavors gaining traction are those that enhance an existing benefit, improve sensory payoff, or fit cleanly into familiar beverage rituals. Novelty works when it is legible and purposeful, not when it asks consumers to relearn how or why they drink.
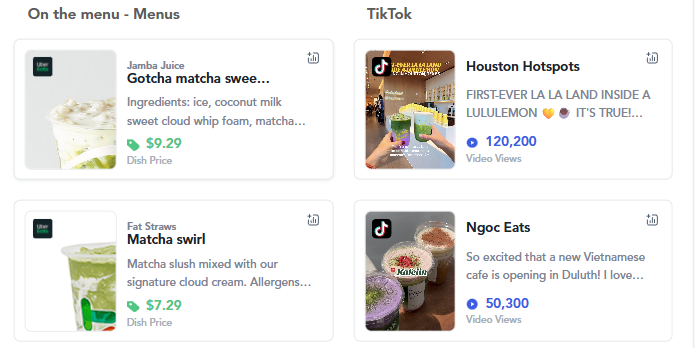
The concept of the matcha cloud illustrates how flavor exploration performs best when paired with a recognizable structure. According to recent matcha consumption data, while the format is still niche in total share, it boasts a +275.6% YoY growth in social discussions and a clear crossover into foodservice with more than 1,600 restaurant placements.The appeal is not matcha alone, but the combination of flavor, texture, and visual presentation within a latte-style format consumers already understand.
Flavor innovation succeeds when it clarifies the product’s purpose and improves drinkability. Formats that require explanation slow adoption, while those that align with existing expectations scale faster.
Intense flavor and real fruit are driving engagement without sacrificing clarity
Across functional beverages, flavor is becoming a differentiator again, but in a controlled way. According to the Social F&B panel, claims tied to intense flavor (+307% YoY) and real fruit (+270% YoY) are accelerating alongside functional benefits. This suggests consumers are no longer willing to trade taste for health, even in wellness-oriented drinks.
Flavor exploration here is additive, not distracting. It supports repeat consumption rather than positioning the beverage as a one-time experience.
Botanical ingredients are gaining traction when flavor does the work
Botanical ingredients continue to show momentum, particularly when they serve a clear sensory role. Botanical claims grew +37.5% YoY, and botanicals now appear in 6.6% of social posts tied to eco-friendly and wellness beverages. However, their performance improves when they are introduced as flavor-forward components, such as berry botanicals, rather than abstract health signals.
Integrating botanical flavors into refreshing, familiar profiles makes them easier to understand and scale, pointing directly to where cocktail culture is heading.
Bone broth drinks extend flavor exploration into savory formats
Flavor exploration in beverages is also moving beyond sweet and botanical profiles. Bone broth drinks show +34.1% YoY growth in social discussions, with recent upward momentum despite a small overall share. The format is gaining traction across home cooking and foodservice, supported by more than 26,000 posts and growing restaurant presence.
Savory flavor works here because the format signals purpose immediately. Bone broth is understood as warming, nourishing, and protein-forward, reducing friction around drinking something traditionally consumed as food. In this case, flavor exploration reinforces function rather than novelty, aligning with the broader shift toward beverages that fit clear routines and use cases.
What should beverage teams validate before launch?
Flavor exploration in 2026 is not about pushing boundaries for their own sake. It is about enhancing function, improving drinkability, and reinforcing format familiarity. Beverages that succeed are using flavor to:
- Strengthen an existing functional promise
- Improve sensory satisfaction without adding complexity
- Deliver novelty within recognizable consumption rituals
For brands, the opportunity lies in choosing flavors that clarify the product’s role rather than compete with it. Identifying the right beverage format is only part of the challenge. Winning retail placement depends on whether the decision can be explained clearly, defended with evidence, and translated into a buyer-ready story.
That’s where most beverage concepts stall. For teams looking to move from insight to shelf, the Winning the Shelf Playbook breaks down how to turn consumer demand signals into retailer-facing logic, what to lead with, what to validate, and how to frame your drink so buyers understand exactly why it deserves space.
A practical checklist for beverage brands entering the market
Before moving a beverage concept toward launch or retail conversations, teams should pressure-test a few fundamentals. These considerations separate ideas that travel from those that stall.
- Is the target consumer clearly defined?
Identify who this drink is for, when they consume it, and what it replaces in their routine. Formats like protein coffee, functional tea, or bone broth drinks work because the audience and moment are immediately legible. - Is the benefit specific and defensible?
Broad wellness positioning underperforms. Anchor the product around one primary need, energy, gut health, calm, recovery, and validate that demand with repeatable evidence. - Does the format align with the function?
Consumers adopt beverages faster when the format matches expectations. Familiar structures such as RTD coffee, soda alternatives, tea, or warm broths reduce friction and support repeat purchase. - Is sustainability tangible, not implied?
Sustainable ingredients or botanical sourcing should reinforce an existing product role. Packaging decisions that reduce waste, improve efficiency, or simplify logistics are easier to defend internally and to buyers. - Does flavor support repeat consumption?
Innovation should improve drinkability, not distract from it. Successful flavor exploration enhances function, reinforces format familiarity, and avoids novelty that limits frequency. - Can the decision be explained simply?
If the concept cannot be articulated clearly to marketing, commercial teams, and retailers, the insight will not travel, regardless of how strong the data looks.
Future outlook: comprehensive beverages forecasts
Tastewise beverages forecasts project where US consumer demand goes over the next 12 months, based on how each trend has moved across the consumer panel, menus, and recipes. Three patterns stand out for product developers and brand executives planning past the 2026 drink trends.
Functional coffee and tea keep climbing. The Tastewise forecast has matcha demand about 11% higher by September 2027, on top of 13% growth in the past 12 months. Protein coffee is forecast to rise by a similar margin through next year. Vegan consumers lead matcha interest and keto consumers lead protein coffee interest, so plant-based milk and sugar-free versions are the natural first tests. If you run an RTD coffee line, a matcha or protein extension sits on demand that is still building.
Functional benefits are narrowing to named outcomes. Among US functional tea consumers, brain function grew 13% over the past year, while medicinal positioning fell 31%. For product innovation teams, that points to leading the pack with one outcome, such as focus or energy, and keeping supporting benefits on the back.
Retail channels are rewarding familiar formats. Sparkling appeared on 258 new US beverage launches in the past 12 months and canned on 201, so sparkling formats remain one of the most common routes onto shelf. The next wave is still small. Protein soda more than doubled among US non-alcoholic beverage consumers since last year but reaches about 0.01% of them, which makes it a candidate for a limited run before a full launch.
Where Tastewise fits into beverage decisions
The top beverage trends shaping 2026 share one pattern. Formats that meet a specific need inside an existing routine are the ones earning shelf and menu space, and teams still have to prove that case internally and to buyers.
Tastewise is the proactive AI food and beverage intelligence system that delivers before you ask. Agents watch your beverage categories and competitors across consumer, menu, and shelf data. They hand your team the finished work, such as the retailer deck or the concept brief, with every figure carrying its source.
FAQs about 2026 beverage trends
Beverage trends in 2026 are being shaped by drinks that align with clear functional needs and repeatable routines. Formats like protein coffee, functional tea, prebiotic soda, and bone broth drinks are gaining traction because they fit existing consumption habits while delivering specific benefits.
Functional beverages perform better when the benefit is specific and easy to understand. Consumers are more likely to adopt drinks positioned around energy, gut health, or recovery than beverages relying on broad wellness or “better-for-you” claims.
Formats that replace familiar drinks scale faster. Ready-to-drink coffee, soda alternatives, tea-based beverages, and warm savory drinks reduce friction for consumers and are easier for retailers to merchandise and justify on shelf.
Flavor innovation matters when it supports function and drinkability. Trends like matcha cloud and botanical-forward beverages show that consumers respond to flavor exploration when it enhances a familiar format rather than introducing novelty for its own sake..
Brands can validate beverage trends by combining social signals, foodservice adoption, and at-home consumption behavior. Using data to confirm who the drink is for, when it’s consumed, and what it replaces helps reduce risk before entering retail conversations.

We’d love to learn your goals and see how Tastewise fits
We’d love to learn your goals and see how Tastewise fits
Get a personalized demo
Good taste. Wise move.
Your demo request is confirmed. We’ll reach out within one business day to schedule your walkthrough.
What happens next

See what’s driving demand, then turn it into a sell-in story for retailers and operators.
- Connect consumer panels, market trackers, and agents into one evidence view
- Get the “why” behind what’s changing, with explainable demand drivers
- Walk away with a buyer-ready narrative and next steps to activate
Trusted by


“Tastewise is my secret tool for knowing what consumers want next and why.“